Usually excluded
- Settling, cracking and shrinking of foundations, walls and floors
- Earth movement, including expansive clay swelling and shrinking
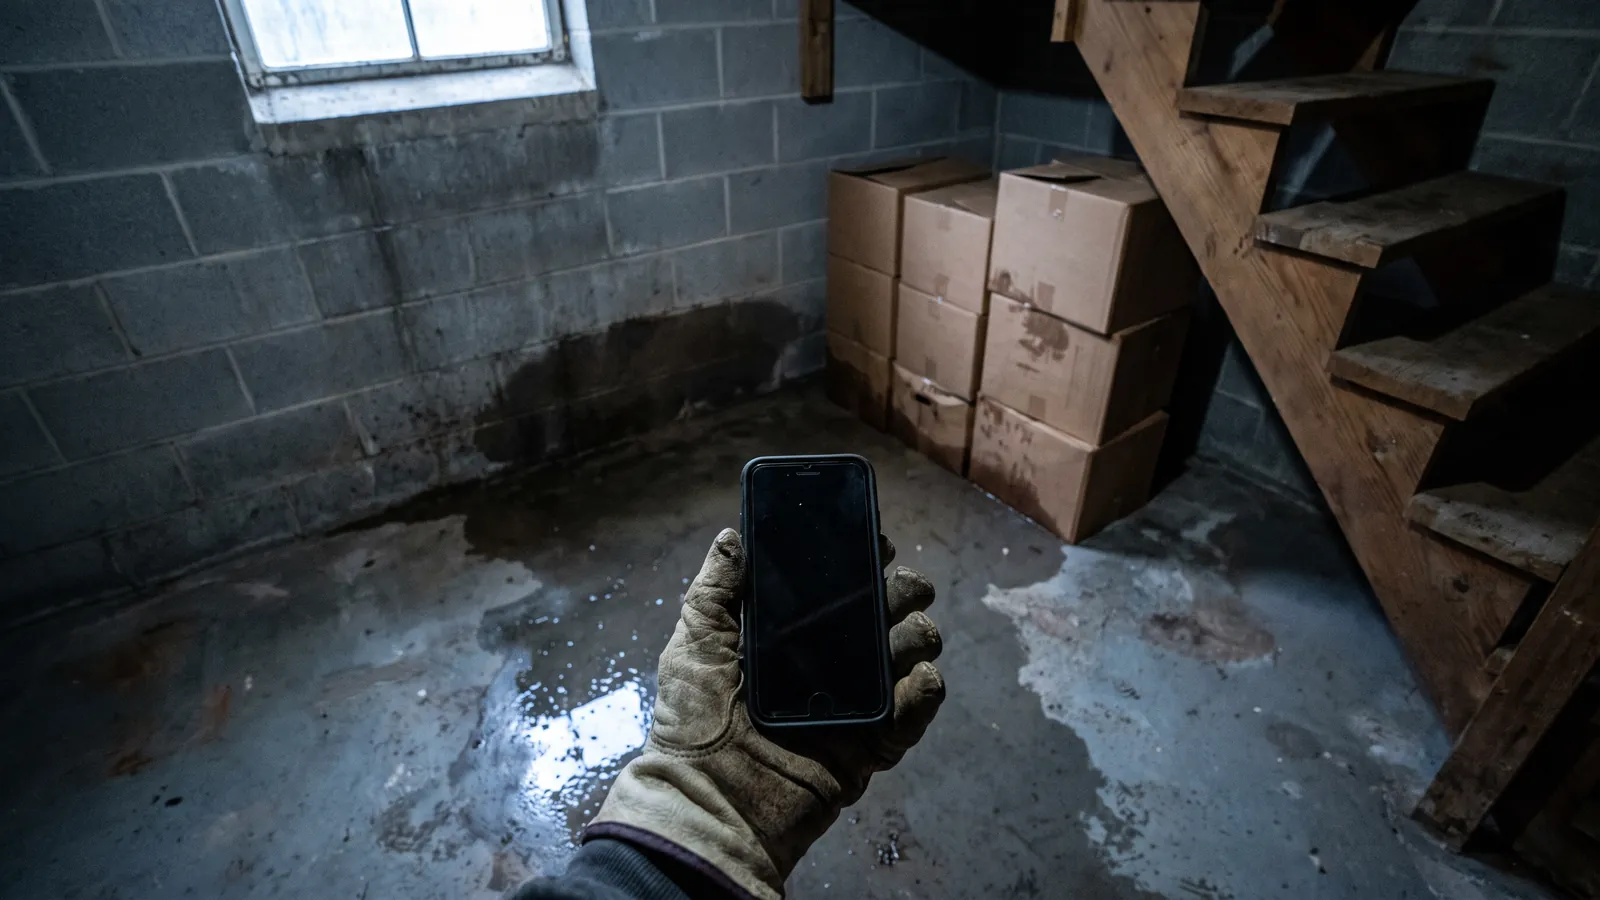
- Groundwater seeping through walls and floors
- Flood water from rivers, creeks or surface flooding, which needs separate flood insurance
- Wear and tear, and damage from poor maintenance
Sometimes covered
- Damage caused by a sudden, accidental water leak, such as a burst supply pipe under a slab
- Sewer or drain backup, if your policy has that endorsement
- Damage from a covered event like a vehicle hitting the house
- Earthquake damage, only with earthquake coverage, which some Missouri homeowners buy because of the New Madrid zone to the south
Every policy is different. Read the exclusions section and the endorsements page of yours, or ask your agent directly.
If you file
- Take dated photos and video of the damage, the cracks and any water.
- Write down when you first noticed it and what happened just before.
- Call your insurer or agent and ask whether the cause is covered before you sign anything.
- Keep receipts for emergency steps like pumping water out or temporary shoring.
- Get a written repair plan and price. Our inspection report can be shared with the adjuster.
If a claim is denied
Ask for the denial and the policy language it relies on in writing. If you think the claim was handled unfairly, the Missouri Department of Commerce and Insurance takes consumer complaints about insurers.
Quick answers
Will you deal with my insurance company?
We can share the inspection report and the written plan with your adjuster. Whether the policy pays is between you and your insurer.
Does flood insurance cover foundations?
Flood policies can cover some foundation damage from a flood event, with their own limits. Check the policy.
Should I repair before the adjuster visits?
Do only what prevents further damage, like pumping water out, and photograph everything first.